Shifting from quantity to quality and profit margin–focused management to build an optimum portfolio for the next generation
- Pursuing overall optimization through CxO coordination and
forging a clear path to an ROE of 8% by FY2027 -
Tadashi Oshima
Oji Holdings Corporation
Director of the Board
Senior Executive Officer
CFO
Summary of Financial Results for FY2025
Despite making progress driving changes to or withdrawing from low-profit businesses in Japan and overseas, consolidated operating profit totaled ¥34.6 billion, well short of our initial target of ¥75.0 billion. Although nearly all of our price increases were ultimately achieved, weak pulp market conditions and delays in realizing the benefits of these increases contributed to the decline.
However, profit attributable to owners of parent increased year on year. This was in part due to higher foreign exchange gains driven by the revaluation of foreign currency–denominated receivables and payables, along with extraordinary income from the sale of lease property and shareholdings.
The slimming of these assets was the result of a policy set out in Medium-term Management Plan 2027 being implemented as planned.
Given the likelihood that costs will continue to rise in the future, we will implement price increases at appropriate times and continue efforts to ensure stable operation and lower costs. Over the remaining term of the Medium-term Management Plan, we will aim for sustainable improvements to operating profit in parallel with ongoing asset slimming efforts.
Path Toward the Goals for FY2027
Shifting from quantity to quality and abolishing the net sales KPI: To advance from the consolidated operating profit of ¥34.6 billion we recorded in FY2025 to ¥60.0 billion in FY2026 and ¥120.0 billion with an ROE of 8% by FY2027, the final year of our Medium-term Management Plan, we will make a further shift toward management focused on capital efficiency. In the future, we aim to reach an ROE of 10%. Given fading domestic demand for newsprint, printing, and communication paper, we have reached the limits of management that pursues expanded volume. That is why under the current Medium-term Management Plan, we made the decision to abandon net sales as a KPI in order to clarify our policy of seeking profit margins over scale and quality over quantity. However, in growth areas where we will take the lead in the shift to a circular economy, such as the sustainable packaging and forest biomass businesses, as we are still at the stage of creating and establishing the market itself, we will pursue sales at a limited scale as a leading indicator of the speed of growth.
Building resilience that is less dependent on market fluctuations: As we work toward achieving our FY2027 target of ¥120.0 billion in consolidated operating profit, overseas pulp market conditions remain one of the key external factors affecting our performance. However, the true aim of our transformation is to move away from dependence on market conditions. To achieve our target profit through our own efforts, we will continue to advance these initiatives with a sense of urgency in FY2026. These include steady price pass-through, a shift to high-value-added products, stable operations and cost reduction, and the restructuring of low-profitability businesses implemented in FY2025. By rigorously executing these measures within our control, we will build the robust resilience needed to achieve ¥120.0 billion in operating profit regardless of the external environment.
Strategic focusing of resources on growth areas and businesses: We will strategically allocate the management resources we have generated to the integration of downstream businesses in India and Southeast Asia that are expected to undergo high levels of growth, as well as the sustainable packaging business that will drive the provision of alternatives to fossil-resource-derived materials. While maintaining our growth investment allocation as a driver of growth, we will carefully select investment allocations for each business based on stringent capital efficiency hurdles, ensuring that resources are concentrated in projects that are expected to generate high profits with truly high added value, in an effort to improve profitability in substantive terms.
Functioning of the CxO system and investments in the next generation: The key to implementing these objectives lies in the implementation of the CxO system introduced in April 2025. We will establish horizontal connections between a vertically siloed COMPANY structure arranged by business to promote Group-wide marketing and overall optimization across the organization. In addition, looking to Long-term Vision 2035, we will continue investing in R&D for the core businesses of the next generation, putting ourselves firmly on track to enhance corporate value in the long term.
Our View of Capital Efficiency in Management Decision-Making
In decisions on investment and business withdrawal, our minimum criterion is whether we can gain a return that exceeds WACC, and we have set hurdle rates for metrics such as EBITDA, operating profit margin, and ROIC. Internally, the concept of ROIC has increasingly taken root. However, there is a tendency for ROIC to appear higher if we continue using existing facilities in the short term, while implementing growth investments can have the opposite effect of temporarily reducing ROIC. For that reason, it is not appropriate to rely on ROIC as a single metric. We combine multiple metrics and carefully assess the rationale for deploying capital across our entire portfolio.
At the same time, in addition to quantitative aspects such as hurdle rates, we also emphasize qualitative aspects such as potential future risks. In situations where it is difficult to make a decision, we verify whether a risk should be taken on while carefully looking at the worst-case scenario within a tolerable level and make final investment decisions from an all-encompassing perspective. I believe that an important role of a CFO is to make decisions on the allocation of capital from the perspective of overall optimization of both quantitative and qualitative aspects without being swayed by personal attachments or past circumstances.
In addition, to reduce the cost of capital and optimize our capital structure, we have raised the maximum acceptable net D/E ratio in Medium-term Management Plan 2027 from 0.7 to 1.0 or less, switching to a basic policy of utilizing leverage. On the other hand, we are carefully monitoring the risk of rising interest rates in the short term. By thoroughly ensuring investment entry management (investment discipline) and post-investment earnings monitoring, we will maintain a balance between financial soundness and improving capital efficiency.
It should also be noted that the pursuit of capital efficiency is not limited to financial capital. Given the rising interest in natural capital accounting around the world, the Oji Group is also actively involved with discussions on the formation of international rules. In the future, we will advance initiatives aimed at appropriately quantifying and visualizing the value produced by the vast forest resources we own (including CO2 absorption and sequestration aimed at carbon neutrality and the effects from the conservation and restoration of biodiversity contributing to nature positivity), and translating that into sustained improvements to corporate value as a new competitive advantage.
“Steward the Forest, Unlock Its Untapped Potential” also aligns with our financial aims. Developing national resilience at the local level is a form of risk management that protects the operations of factories and mills while safeguarding assets, while economic security at the national and regional levels brings stability to procurement costs through company-owned forests. In addition, investments in sustainable packaging and the forest biomass businesses toward solving environmental issues at the global level serve as a growth engine expanding future cash flows and enhancing PBR.
Toward Enhancing the Profitability of Our Existing Businesses
To enhance the profitability of our existing businesses, we will establish steady price increases as an ongoing pricing strategy rather than a one-off increase. Given the likelihood that costs will continue to rise in the future, we will formulate strategies early on and implement price increases while obtaining the understanding of stakeholders in an effort to maintain and improve our profit margins. More recently, implemented price increases for printing and communication paper in October 2025 and August 2026, and for corrugated containers and related products in October 2025, as part of efforts to improve profitability.
It is also important to carefully assess whether to continue supply in connection with products and sites that cannot maintain profit margins at a certain level. Although there are prospects for earning survivor profits by continuing to supply products to the end in a market with contracting demand, if we retain our responsibility for supply while earnings remain low, there is a risk of continually facing declining utilization rates and a high cost structure. However, there are concerns that making these decisions in a mechanical fashion could compromise employee engagement, and we will continue to make decisions from the perspective of overall optimization while taking into account the impact on the front lines.
Background to the Revision of the Cash Allocation Policy
In response to cash flow from operating activities declining from an expected ¥500.0 billion to ¥410.0 billion over the course of the Medium-term Management Plan, we made a flexible revision to our cash allocation priorities to align with changing conditions.
First, upkeep CAPEX contracted from ¥220 billion to ¥180 billion, but as these investments are directly linked with safety and stable operation, we do not intend to make across-the-board reductions. We will carefully assess which sites will receive ongoing investment with a view to our future business portfolio, and strike a balance between maintaining our business infrastructure and improving efficiency by identifying failures at the early stages through day-to-day preventive maintenance and the utilization of DX. On the other hand, investments in new business creation, including R&D, and in the expansion of existing businesses that show promise rank extremely low in priority for reductions, even if there are aspects that will reduce cash inflows. Our latest revisions to these investments (in R&D and growth) from ¥320 billion to ¥300 billion are related to quality improvements as a result of strict screening of investment projects and do not represent a retreat from our strategy.
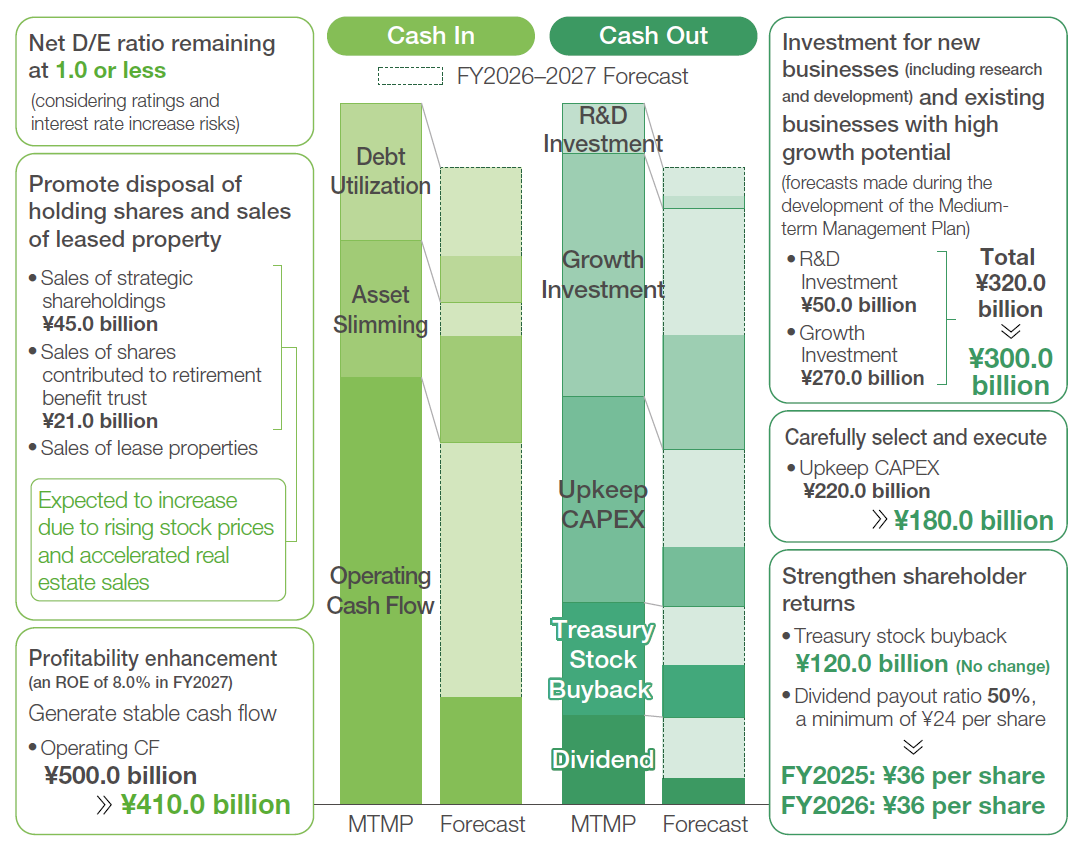
In addition, to address funding shortfalls, we will significantly accelerate and expand initially planned reductions in cross-shareholdings, the sale of shares contributed to retirement benefit trusts, and the sale of lease property; strengthen our ability to generate cash; and carefully consider risks such as rising interest rates, while giving top priority to ensuring financial soundness. We will flexibly inject the necessary working capital and investment capital with the use of interest-bearing debt while maintaining a net D/E ratio that does not exceed 1.0.
Through this approach of prioritizing the generation of cash through improved asset efficiency, we will balance our commitments to maintaining the growth investment allocation and improving shareholder return with a dividend payout ratio of 50% and ¥120 billion in treasury stock buybacks over three years.
The Role of the CFO in Governance
The role of a CFO is to go beyond partial optimization and seek overall optimization in order to maximize corporate value. I take part in all investment decisions, and while I have opportunities to “step on the accelerator” with things like the construction of a new plant in Vietnam or strengthening inter-site coordination through M&A actions in Europe and India, there are times when I need to firmly “plant my foot on the brakes” when reassessing businesses, such as when we implemented a partial withdrawal in New Zealand and Australia in FY2025. That is how we maintain a healthy portfolio.
With M&A activities and strategic capital investment in particular, our responsibilities do not end with executing the investment; it is important to engage in continuous monitoring to ensure profitability and synergies thereafter. I believe that in addition to the entry point of investment, verifying and reassessing the progress of the investment afterward is a vital governance function fulfilled by a CFO.
I also look at opportunities such as collaboration with start-up companies that are more than mere extensions to our existing technologies and frameworks, as part of efforts to explore the potential for new business expansion.
Key Points in Dialogue with the Capital Markets
In communications with institutional investors and other stakeholders, I emphasize the need for them to gain a deeper understanding of the Oji Group. Since FY2025, we have been holding quarterly financial results briefings, and as CFO I also try to attend meetings with investors and analysts as much as possible to provide opportunities for direct dialogue.
We promptly share the feedback received in these meetings with top management and use it to recognize management issues and consider what measures to take. One result of that feedback is in our quarterly summary of financial business results, where we have made improvements to provide per-sector analyses and disclose breakdowns of the factors causing positive and negative variances. By disclosing the challenges we face rather than only positive news, we allow for more in-depth points of discussion when engaging in dialogue and create opportunities to incorporate more outside perspectives into management.
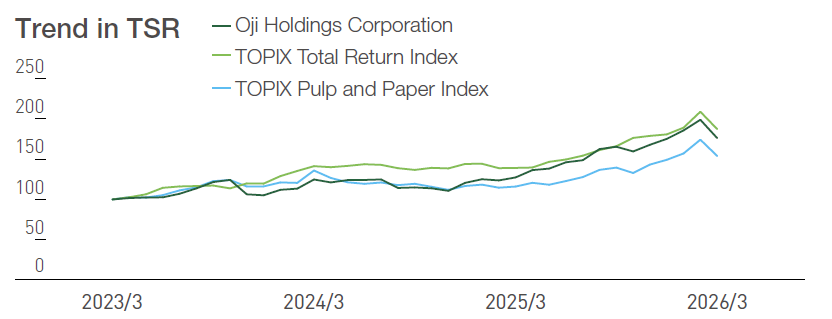
I believe that total shareholder return (TSR) is a key metric for assessing how the capital markets rate the results of those efforts. Over the past three years, our TSR was +76.2% (+20.8% on an annualized basis). While this was slightly below the TOPIX Total Return Index, it was above the TOPIX Pulp and Paper Index, which tracks trends in the same industry. The Oji Group is working to enhance shareholder returns and has strengthened returns with a target dividend payout ratio of 50% based on its policy of stable dividends. Going forward, we will enhance the quality of dialogue, pursue enhanced earning capabilities and management focused on capital efficiency, and translate those efforts into the sustainable enhancement of corporate value.
- *1The above graph shows the change in total shareholder return (TSR), which is the total return combining appreciation of share price and dividends, up to the end of March 2026, assuming investments were made in Oji Holdings, TOPIX, and TOPIX (Pulp and Paper) at the end of March 2023.
- *2 Each of the figures indexes the investment amount as of the end of March 2023 to 100. For Oji Holdings, TSR is calculated based on the share price combined with dividends paid during the period, on the assumption that dividends are not reinvested. The TOPIX and TOPIX (Pulp and Paper) used for comparison are both total return indexes that incorporate dividends.